
As a stockpicker, this market is a bit like being a kid in a candy shop: plentiful special situations, stocks hovering around all-time lows, and reasonable levels of “fear.”
In last week’s Portfolio Update, I mentioned several new holdings recently added to the portfolio (plus a few more that are “on deck” right now).
In this post, I’m sharing a brief “post mortem” on recently closed/exited holdings, a full rundown on all 14 active recommendations and 4 stocks where I'd be putting fresh money to work right now.
Closed Positions
Since April 2026, I’ve closed 8 positions for an average return of around 30%.
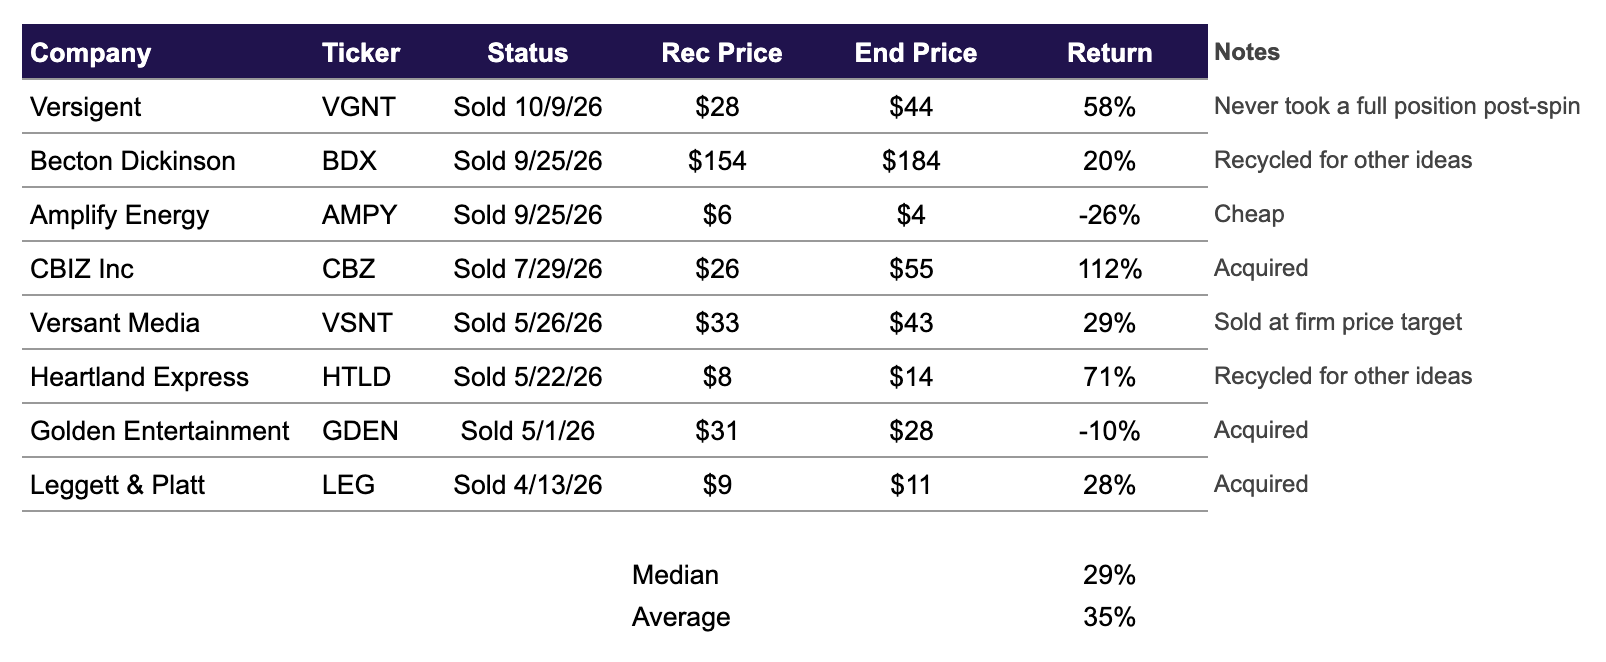
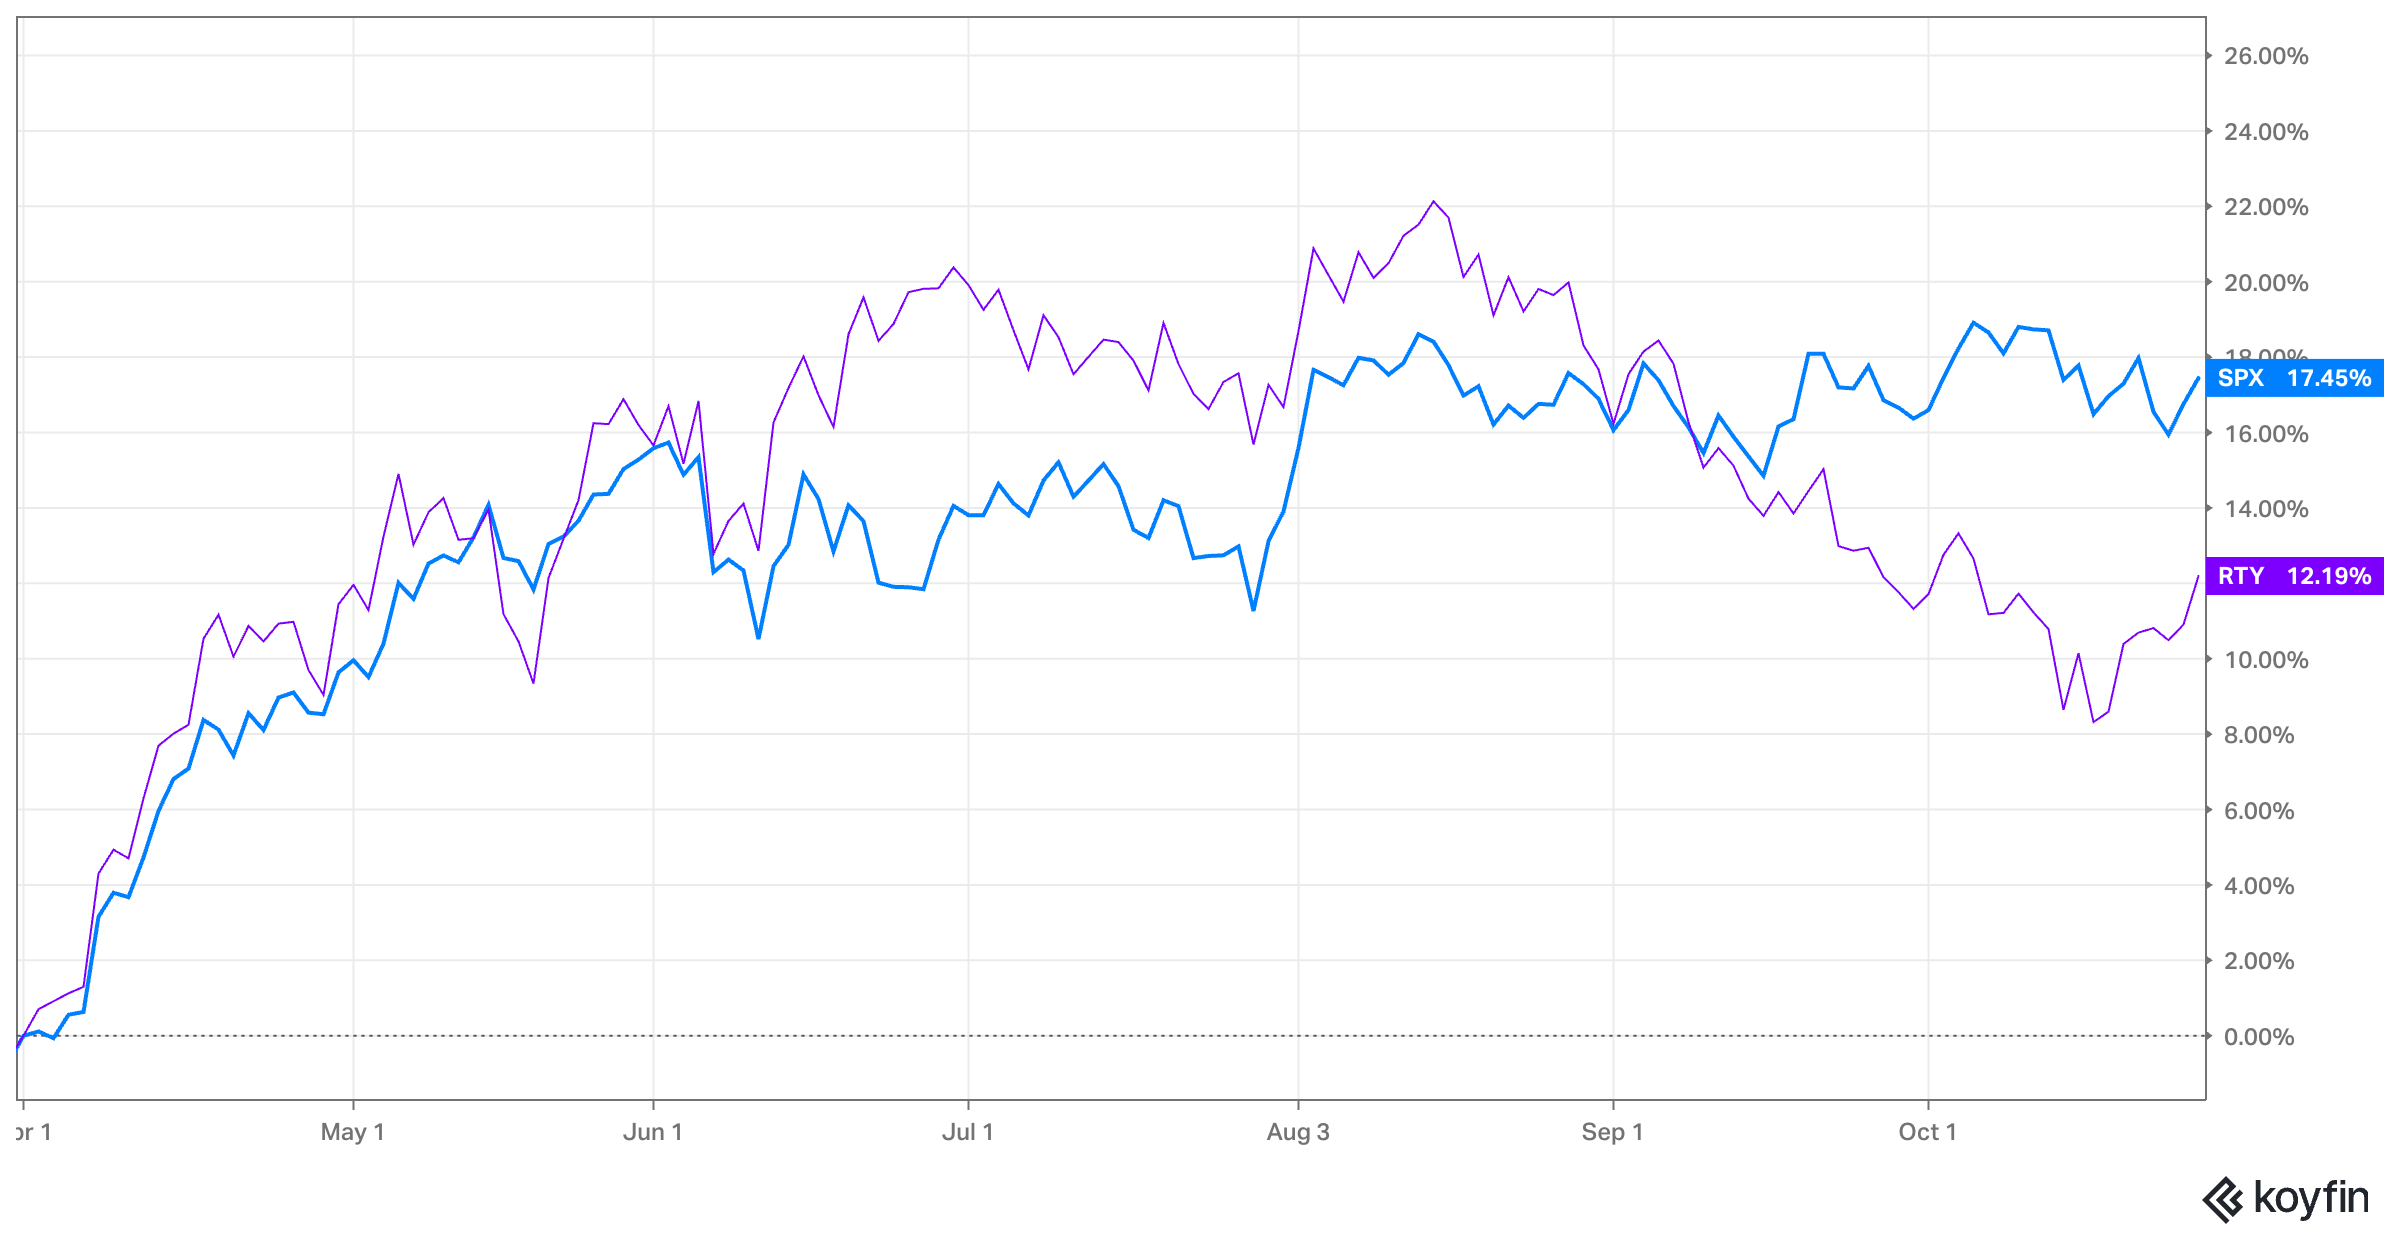
During that timeframe, the S&P 500 is up ~21% and Russell 2000 ~15% (with a nice little correction from August to October tucked in there):
Here were some notable ones:
CBIZ (CBZ)
Result: acquired at a 100% premium
Maybe more than a bit of luck involved with this one.
I originally purchased shares in March 2026 at $26 after they were pummeled from a combination of AI fears and levered M&A (which resulted in capital allocation moving from tuck-in acquisitions to debt paydown).
It was one of the more extreme re-ratings I’ve ever seen, from 20x earnings to 7-8x seemingly overnight.
The business was still generating healthy cash flow and private equity buyers were still busy acquiring firms at huge multiples of EBITDA.
A few months later (July 2026), Grant Thornton announced a buyout at $55 with the help of private equity.
Becton Dickinson (BDX)
Result: Sold at a 20% gain
This was an RMT/spin-off transaction with Waters Corp (WAT) which resulted in a cheap healthcare stub. I rode that stub business for a few quarters as it re-rated and sold for a modest gain (just shy of my initial price target).
Ironically, I would have been better off leaving the exposure to Waters as that stock has done extremely well! Oh well, I isolated for the specific bet I was making at the time.
Amplify Energy (AMPY)
Result: Sold at a 26% loss
In January 2024, I was excited about AMPY for two reasons: (1) they had extremely long life oil & gas assets with 12+ years of production capacity; and (2) the stock was trading at half of their PV-10 value with positive cash flow.
Since then, they’ve replaced management after an attempted bad acquisition, sold some assets to shore up the balance sheet, and now they’re heavily reinvesting in an offshore oil field (outspending cash flow for the foreseeable future).
At $4, the stock is trading at half of book value and might be cheaper today than my original write-up, but the story is different with a strategy centered around growing production as opposed to generating and returning cash.
You could call it a management change situation, but it doesn’t fit my value + special situation criteria as much today.
Versant (VSNT)
Result: sold at price target for 30% gain
This was the cable network spin-off from Comcast back in January 2026. It was quickly labeled as a melting ice cube and shares were pummeled from $47 to $28 right out of the gate. As the valuation approached 3x EBITDA and volume surpassed the entire share base, I took a position thinking this was heavy technical selling from the distributed shares (hey, it was a 15:1 spin ratio).
It was always meant to be a trade.

The stock recovered by 30% over the next few months and I sold around $43.
For a moment, I thought about “holding on for more” since it was still pretty cheap and the market was a little less pessimistic on cable networks. I still didn’t love the long-term view on the business and much preferred the business mix at Starz.
So I held firm to my price target and sold the entire position. Since then, shares are rolling over (back to $30, below my original purchase). This time it doesn’t have the technical spin-off factor, so I’m unlikely to get involved again.
Leggett & Platt (LEG)
Result: acquired by Somnigroup (SGI) in an all-stock deal
I was disappointed in this one because they had finally cleaned up the balance sheet such that a serious capital allocation inflection was around the corner. I spent some time reviewing SGI, and although I think they’ll do well, it’s not my “cup of tea” and I sold LEG for a nice gain.
Full Portfolio Rundown
I think about my portfolio/recommendations in 3 buckets:
